Meet Med Mutual Protect at The Brokerage
The 70-Year-Old Carrier Most Agents Don't Know
Here is a strange fact about one of the more useful carriers in the alternative-coverage space: it has been operating since 1956, and most agents have no idea it exists.
That is not an accident. Med Mutual Protect spent most of those decades as a captive shop, which is exactly why the independent world never got to know it. It started life as Reserve National in Oklahoma City, built to serve rural communities that had no access to group health insurance. It was acquired by Kemper and rebranded as Kemper Health, and a few years ago it was acquired again, this time by Medical Mutual of Ohio, the largest health insurer in that state. The name on the door now is Med Mutual Protect. What has not changed across all of it is who they serve: people who do not get coverage through an employer, people who looked at the marketplace and found it unaffordable, and people the marketplace simply has not worked for.
For agents watching the ACA landscape shift under their feet, that last sentence is the whole opportunity. So it is worth understanding what MMP actually brings to the table.
Products you can sell one at a time
The first thing that makes MMP unusual is the structure. The products are offered a la carte, which means you do not have to sell one thing to unlock another. There are three core products: a specified disease policy, an accident policy, and a fixed indemnity plan. They can be bundled together into something that functions like comprehensive coverage, or any one of them can stand on its own.
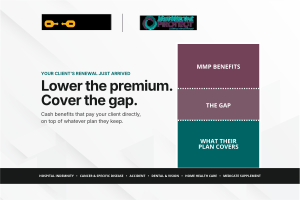
That flexibility is the point. If a client already has an ACA plan but is exposed on a large out-of-pocket maximum, you do not have to replace anything. You find where they actually feel at risk, whether that is a surgery, an accident, or a serious diagnosis, and you plug the specific product into that gap. If a client has no coverage at all and cannot afford the marketplace, you can build something from the same three pieces that protects them against the things that would genuinely wreck them financially.
A few features are worth knowing because they answer the questions agents ask first.
The hospital indemnity pays its defined benefit regardless of what other coverage the client has. There is no primary-versus-secondary game, no waiting for another plan to pay first. If the client has coverage elsewhere and it pays, MMP still pays its benefit in full. It was refreshed recently, and one of the more agent-friendly changes was simplifying the old surgery schedule down to three clear categories. When a client calls and asks what a procedure will pay, the agent can actually answer without decoding a complicated table.
The specified disease policy is the one newer agents tend to misunderstand. The list of covered conditions looks short at first glance, but it covers entire systems rather than individual ailments. Cardiovascular means anything in the cardiovascular system. Gastrointestinal means anything in that system. Cancer, heart attack, and stroke are covered, and because the design can evolve, conditions that did not exist as concerns years ago are now included. It is built around a deductible and co-insurance structure rather than a fixed payout, which matters a great deal when a large claim hits.
The accident policy is the straightforward one: a broken bone, a laceration, a concussion, the ordinary catastrophes of being a person in the world.
Underwriting that says yes more often than agents expect
For agents who have only ever sold guaranteed-issue ACA, medical underwriting can feel like a wall. MMP has worked to make it a low one.
The process is short, built around a handful of questions the agent reads directly to the client, plus a prescription check. There are no phone screens with the client and no pulling of medical records. The company is deliberately putting trust in the agent to understand the process and present it accurately.
The look-back window is where MMP separates itself from a lot of the alternative-coverage field. Where some carriers look back ten years, or forever, MMP uses a five-year look-back. A client who had a serious illness years ago, was cleared, and has stayed clear becomes eligible, and if that condition ever recurred, it would still be covered. Everyday conditions that agents worry about, like blood pressure and cholesterol, are not treated as knockouts and are not even counted as pre-existing. Tobacco use is not a decline either; it carries a rate-up instead. There are genuine knockouts, the serious chronic conditions and active treatments where the marketplace is the right answer, but the net is wider than most skeptical agents assume walking in.
Claims built for a good client experience
None of the above matters if claims are a nightmare, because a bad claims experience is how a client loses faith and cancels, and how an agent quietly stops offering a product. MMP has structured its claims process to avoid the worst version of that.
They participate in a national network, but network participation is not required for coverage, and there is no balance billing for out-of-network care. The process works in steps. If the provider is in network, the client gets network repricing. If the provider is out of network but will still file, the claim gets paid without balance billing the client. And in the rare cases where a provider will not file at all, there is a dedicated team that handles reference-based pricing conversations directly with the facility. The goal at every step is to keep the client whole and the experience smooth.
There is also a cash-pay angle worth teaching clients, because the products reimburse the same whether a service was run through the network or paid in cash. For smaller, shoppable services, the cash price is often dramatically lower than the billed insurance price, and the client can pay it, submit the receipt, and get reimbursed at their benefit amount. It is a different way of thinking about health coverage, and part of the agent's job is opening the client's mind to it.
Why this belongs in your book now
The case MMP makes to agents is not built on hype. It is built on staying in one lane for seven decades and knowing it cold. They have fourteen years of data on how these specific products perform, which is how they price them to last. They are not chasing short-term medical or launching annuities. They know what they are, they operate in more than thirty states, and they intend to be here.
For an agent, the appeal is stability plus fit. The underwriting is lenient enough to say yes often, the products are simple enough to explain and for clients to understand, and the claims process is built to keep clients happy, which keeps them on the books and keeps the agent from getting burned. In a market where ACA changes, Medicare commission pressure, and shifting carrier participation are all squeezing at once, a durable, flexible, affordable option is not a nice-to-have. It is diversification, and diversification is what separates the agents who grow from the agents who get left behind.
Get started
If you want to add Med Mutual Protect to what you offer, the path is simple. Get contracted with MMP through The Brokerage Inc., and attend one of our trainings so you can present these products with confidence. The agents who learn this now will be ready when their clients need it, which, given where the market is headed, will be soon.
Get appointed. Then get trained.
Path inside Broker Link:
Get Contracted > Request Contracts > Med Mutual Protect.
Discover more about Med Mutual
Want more on what's driving affordability conversations right now?
Register for the Webinar
Join the training webinar on September 24 at 11am
[DT1]https://my.thebrokerageinc.com/contracting/request-contracts/?referer_breadcrumb=1
